

News
September 3, 2026
How Can Labeled Bonds Accelerate Climate Investment in Brazil?
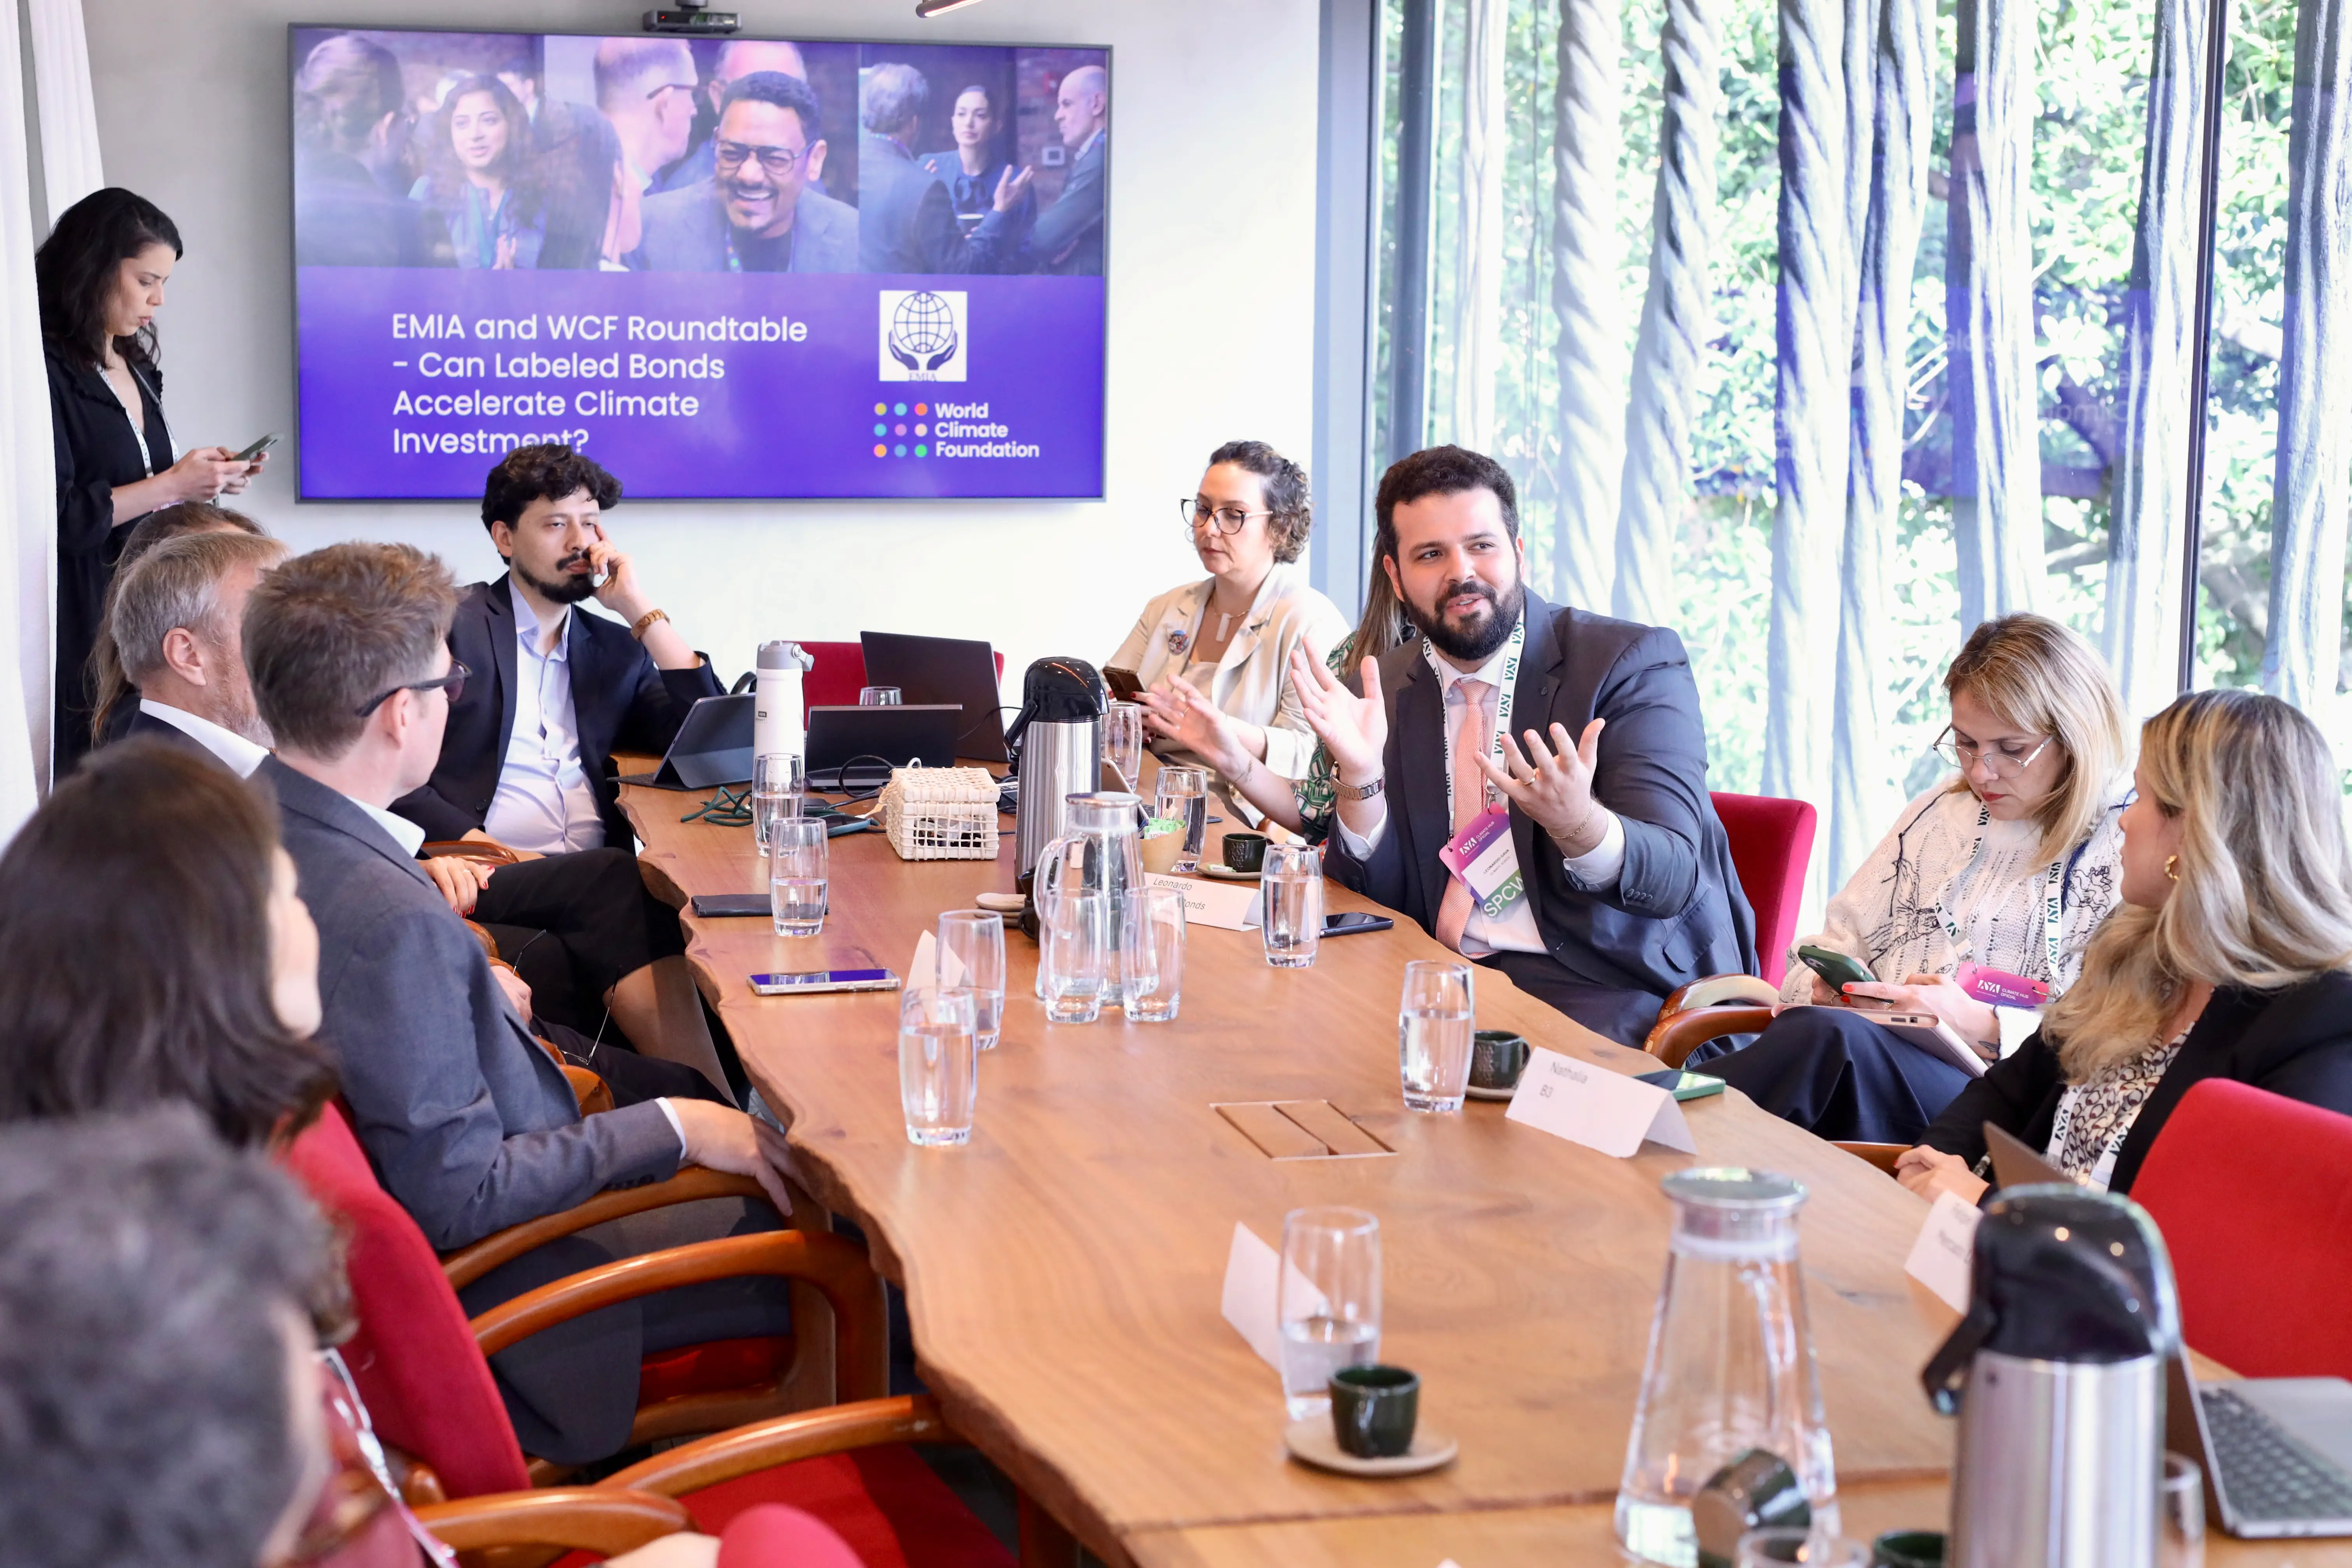
*The information and conclusions in this report come from an in-person roundtable held on August 4 during São Paulo Climate Week. The meeting was co-organized by the World Climate Foundation and the Emerging Markets Investors Alliance under the initiative of the Global Climate Finance Forum (GCFF).
Are we facing a worrying decline in labeled bond issuances in Brazil? The answer is not simple, and major players in the sector offer different perspectives on the problem.
Some prominent market players point out that issuance volume has increased (approximately 20% higher in 2025 than in 2024, driven by high domestic interest rates), while the number of new issues has decreased (approximately 10% lower in 2025 than in 2024), continuing a decline that began in 2021.
Others express greater concerned, noting that investor appetite for labeled products has waned and that the market stands at a critical juncture: the increased costs of reporting and standardization are not clearly offset by a visible benefit, which risks undermining market credibility.
Still, some analysts frame this issue within a broader context, pointing out that the apparent decline in demand for labeled bonds largely reflects the overall slowdown in the post-2021 bond market, rather than a problem specific to labels. In fact, the labeled share of total issuance continues to grow. According to this view, financial fundamentals (risk/return) ultimately outweigh the label itself in investment decisions.
Despite these differing perspectives, there is consensus on one structural factor: exchange-rate risk. U.S. dollar-denominated income is often held abroad rather than converted to reais because the loss from conversion can outweigh returns at the SELIC rate. Exchange-rate protection mechanisms, such as Eco Invest, are the priority solution.
CREDIBILITY, STANDARDS, AND GREENWASHING
The quality of post-issuance information in Latin America is poor. Labeled bond markets lack the comparability provided by credit ratings through an effective "oligopoly" of three agencies; the proliferation of frameworks makes it difficult to compare issuances; and post-issuance sustainability metrics are not usually linked to the actual terms of the bond.
This diagnosis reflects concerns raised by organizations and market participants familiar with green bond reporting and transparency in Brazil.
From the private sector, the diagnosis is even harsher: investors may be indifferent to or misinformed about what the label truly represents. This creates a pricing paradox: accurately assessing and pricing climate risk may make an instrument less commercially attractive, discouraging market participants from doing it correctly in the first place.
Issuers face additional difficulties: they incur penalties (step-up costs, reputational risk) for failing to meet sustainability targets, but reap no tangible benefits from achieving them.
RISK REDUCTION, CREDITWORTHINESS IMPROVEMENT, AND THE ROLE OF THE PUBLIC SECTOR
In China, sustainable investment has become commonplace because it is linked to national strategic priorities (energy independence, import substitution) rather than being framed as "green for the sake of being green." Transition financing expands once it becomes a genuine economic opportunity.
In Brazil, subsidized-loan instruments (e.g., Eco Invest) are currently performing better in this area than the bond market. Brazil’s adoption of no-till agriculture from the 1980s onward provides a related example and model. These farming practices were adopted for economic rather than environmental reasons, but have produced real environmental co-benefits.
Some organizations point out that methods for measuring sustainability impact remain self-designed and potentially biased. Thus, labeled products may follow two possible trajectories: becoming governance standard for assessing suitability, as in China's ESG approach, or becoming an additional source of revenue, similar to carbon credits. Brazil's large domestic market means that most Brazilian companies do not need to issue internationally, and doing so may raise financing costs due to Brazil-specific risks, including foreign-exchange (FX) risk.
Foreign investors ultimately price these risks into their decisions, increasing the cost of international issuance. Therefore, there is no single solution, and the market must find ways to "monetize" the sustainability dimension through private sector mechanisms rather than relying primarily on government support.
Subnational borrowers can often access Treasury-guaranteed loans at competitive rates without taking on the additional tracking and reporting requirements of labeled instruments, reducing the incentive to issue labeled bonds.
DOMESTIC CAPITAL, PENSION FUNDS, LIQUIDITY, AND TRANSITION BONDS
The public financial sector is developing solutions to this situation. In a high-rate environment, with asset managers targeting returns around inflation plus 7–8%, pension fund managers can often achieve inflation plus 5–6% with low-risk government debt. This reduces the relative appeal of taking on private-credit risk through labeled bonds. The tax exemption for infrastructure debentures creates strong investor appetite, and some issuers are reportedly reclassifying projects as "infrastructure" to access it—an incentive model that could potentially be extended to green bonds.
The profitability targets of Brazilian pension funds are close to the SELIC rate, which drives allocations toward sovereign debt rather than private-placement risk. Unlocking greater allocation to labeled instruments would require regulatory changes. Possible measures include requiring all bonds—not only earmarked bonds—to disclose the specific use of funds and establishing a mandatory shared database for monitoring and oversight.
Ultimately, participants emphasized that the barrier to sovereign and sub-sovereign issuance is not necessarily a lack of investor appetite, but the difficulty of building, aggregating, and monitoring eligible project pipelines, particularly at the state and municipal levels.
The discussion therefore converged on a common question: How can transaction costs for investors be reduced, and how can fragmented bioeconomy projects be aggregated into investable structures?